What interchange-plus means
Interchange-plus is a way to price card processing in separate parts. The applicable interchange charge, card-network charges and the processor's disclosed markup contribute to the merchant's total. A quote might describe its processor markup as a percentage of sales plus a few cents per transaction. The word "plus" means that markup sits on top of underlying card costs; it does not mean the quoted percentage is your entire processing rate.
The separation makes a useful question possible: which charges are underlying card costs, which are the processor's charges, and which are fixed fees for the account or tools? It does not guarantee the lowest total bill. A low markup with a large monthly fee can lose to a higher markup with few fixed costs. The answer depends on your sales volume, transaction count, card mix and how customers pay.
Visa explains that interchange reimbursement fees are transfers between the acquiring and issuing banks. Merchants pay an acceptance charge to their financial institution under their own agreement, rather than paying an interchange fee directly to Visa. Mastercard likewise describes interchange as one component of the merchant discount rate. Their explanations and published tables are available at Visa's merchant fee page and Mastercard's merchant interchange page.
What a 0.5% quote meant for AutoTech
In Payment USA's work with AutoTech, an automotive business, the merchant believed its processing rate was 0.5%. Our statement review found an actual 3.25% effective rate. The 0.5% described processor markup above underlying card costs, not the full bill. Payment USA subsequently brought the account's effective rate to 2.8%.
At approximately $75,000 in monthly card sales, those rates imply $2,437.50 before and $2,100.00 afterward: an estimated $337.50 monthly difference, or $4,050 over twelve months at the same volume and effective rates. These dollar amounts are calculations from Payment USA's reported experience, not exact invoice totals or a verified twelve-month savings result. Card mix, volume and additional costs can change the outcome. The full AutoTech comparison shows the arithmetic and assumptions.
This is why we explain the statement before presenting another percentage. Interchange-plus makes the processor's markup easier to identify, but merchants still need to see underlying card costs and additional fees. We also explain “discount” terminology and check whether Amex fees are billed separately. Payment USA never charges a cancellation fee on any account we offer.
The three variable parts of a transaction
Interchange varies by the card and transaction category. A debit transaction, a consumer credit transaction and a commercial card sale can qualify for different categories. How the card is presented, merchant category, transaction data and other network criteria can matter. The card networks publish schedules with many rows, so a single "average interchange rate" cannot describe every merchant's mix. The relevant rate may also include a fixed per-item amount.
Network fees and assessments are a separate set of card-brand charges. Depending on the network and transaction, they may have percentage, per-item or other components. Statements sometimes group these under "assessments" or "dues and assessments"; other network charges may appear separately. Ask which charges the provider passes through and whether any are marked up. Do not assume every line labeled "network" has the same fee base or treatment.
Processor markup is the provider's stated charge above those underlying costs. For example, "interchange plus 0.25% plus $0.10" describes a hypothetical markup: on a $100 sale the percentage piece is $0.25 and the per-item piece is $0.10, for $0.35 of markup. Interchange and network charges are additional. Your actual quote may use a different formula, and the agreement may include gateway, authorization, monthly, PCI, batch or other charges outside that per-sale markup.
This distinction is why an interchange-plus quote should show both the variable markup and the account's other fees. It is also why an advertised flat rate and a quoted "plus" markup cannot be compared as percentages without doing the math.
A $100 example, with every assumption visible
Assume a $100 card sale. For teaching purposes only, suppose the applicable interchange is 1.80% plus $0.10, network charges total $0.15, and the processor markup is 0.25% plus $0.10. Interchange is $1.90; the assumed network charges are $0.15; processor markup is $0.35. The variable transaction cost is $2.40, or 2.40% of this one sale. None of these assumptions is a Payment USA quote or a prediction of the rate your customer's card will receive.
Change only the hypothetical interchange to 2.40% plus $0.10. The variable total becomes $3.00, or 3.00%. The processor's stated markup remains $0.35 in both examples. This is the central tradeoff: the markup can be visible and stable while your all-in effective rate moves with the underlying transactions. On a small ticket, even a ten-cent item fee takes a larger share of the sale than it does on a large ticket.
If your provider also charges $25 a month, that charge belongs in the monthly or annual total. It should not be silently treated as though it were already in the $2.40 transaction example. The same is true for a gateway subscription, equipment charge or annual fee.
Why ticket size and card mix change the answer
Consider two businesses with $20,000 of monthly card sales. Business A has 200 transactions averaging $100. Business B has 1,000 transactions averaging $20. Under the hypothetical processor markup of 0.25% plus $0.10, A pays $50 in percentage markup and $20 in item markup, or $70. B pays the same $50 percentage amount but $100 in item markup, or $150. This comparison isolates markup; underlying interchange and network fees would have to be added for both businesses.
Now imagine the transaction counts are equal but one business takes more debit and another takes more rewards or commercial credit cards. Their applicable interchange could differ substantially. The same effect appears when a merchant shifts from in-person sales toward links, online orders or keyed phone payments. Use the real channel and card mix from your statements; do not apply a countertop rate to remote transactions. The processing fees comparison shows how changing assumed underlying costs can reverse a provider comparison.
No single provider or pricing model is universally cheapest. Interchange-plus can make a provider's margin easier to inspect, but a flat-rate offer may be operationally simpler or less expensive for a particular merchant after fixed fees and services are counted. Tiered plans need the same total-cost test: a "qualified" headline rate does not say how many of your transactions will actually enter that tier.
Read the full monthly statement
Start with the processing period, gross card sales, transaction count, refunds and separate card groups. Then identify interchange, network charges, processor markup and all other fees. Some statements show detailed categories; others aggregate lines. Ask your provider for enough detail to reconcile the totals to the agreement and the network cost categories. Our merchant statement guide walks through the broader statement-reading process.
An effective rate is total fees divided by the corresponding sales volume. For example, $720 in processing charges on $30,000 of matching card sales is 2.40%. This describes that period's observed total, not a promise about next month. Ensure numerator and denominator cover the same dates and cards. If Amex is billed separately, obtain its fee record rather than dividing partial fees by all sales. If a statement includes a refund-heavy or annual-fee month, explain that context before projecting it across the year.
To estimate the provider's markup, first confirm which lines are actual pass-through interchange and network charges, then subtract them from total fees. What remains may include the quoted per-sale markup and fixed or optional service fees. Dividing the remainder by sales produces a blended figure, but it is not the contractual percentage markup. Examine the line items before assuming an unexplained difference is processor profit.
The Payment USA statement analyzer sometimes uses 2.65% as an illustrative comparison benchmark. That figure is not a card-network interchange rate, a guaranteed savings target or a personalized Payment USA offer. Your current effective rate and any proposed pricing should be calculated from matched statements and a written proposal.
Count monthly and annual charges once
Suppose a proposal estimates $500 in processing and monthly charges each month and includes a $99 annual account fee. The annual cost is 12 × $500 + $99 = $6,099. For a budgeting average, that is $508.25 per month. On the actual statement when the annual fee is charged, however, the full $99 appears in that month. Do not add it twelve times or hide it from a month-to-month explanation.
Ask about monthly account fees, gateway or software subscriptions, PCI-related charges, authorization and batch charges, equipment, dispute fees and cancellation terms. Some charges may not apply to your account; the point is to request a complete schedule and compare each provider on the same required tools. A quoted 0.20% markup could cost more than 0.30% markup if its fixed charges are large enough for your volume. At higher sales, the percentage difference may become more important. Run both a quiet month and a busy month through the proposals.
Refunds and disputes deserve their own line in the comparison. Ask whether transaction fees are returned on a refund, whether a separate refund fee applies and what a dispute costs. These policies are provider-specific. A business with frequent cancellations can have a different total than a business with the same gross sales and almost no refunds.
Compare a written quote with your own transactions
Collect two or three recent full statements, including any separately billed card networks. Note monthly volume, number of payments, average ticket, debit and credit mix, and the share that is in person, online, linked or keyed. Include seasonal highs and lows. Send every provider the same profile and ask for a written cost projection broken into underlying card costs, processor markup and fixed charges.
Next, verify the exact scope of the offer. Does it cover the gateway and features you actually use? Are card-present and card-not-present sales priced differently? Is the markup applied to gross sales, net sales or another base? What happens when network fees change? What agreement term, equipment obligation or termination charge applies? A clear answer is more useful than a promise that you will "save up to" a percentage.
When you compare, keep the underlying-cost assumption consistent. One proposal should not appear cheaper merely because its salesperson assumed a low-cost debit mix while another used your real rewards-card sales. If a provider will not explain its assumptions, ask for a revision. The decision can then include support, reporting and workflow quality alongside dollar cost.
Payment USA offers a statement review and can prepare a proposal based on your actual business. That review should be judged by the same standard as any competing quote: matched sales data, a complete fee schedule and clearly labeled assumptions.
Sources and scope
The fee structure explanation was checked September 16, 2026 against Visa's interchange overview, Visa's U.S. interchange schedule, and Mastercard's interchange explanation. The AutoTech account was supplied by Payment USA in September 2026; its estimated dollar savings are derived from the reported rates and approximate volume. Other numerical examples are fictional arithmetic illustrations, not customer results, published network rates or provider quotes. Published schedules and provider terms can change; check current documents when deciding.
Frequently Asked Questions
Is interchange-plus always cheaper than flat-rate pricing?
No. It separates underlying card costs from processor markup, but the total also depends on your card mix, ticket size, channel and fixed fees. Compare complete written offers using the same transactions.
Can I negotiate interchange?
An ordinary merchant generally negotiates its acceptance agreement and processor markup, not the published network interchange categories. Ask the provider to distinguish passed-through costs from its own charges.
What is a good interchange-plus markup?
There is no single good percentage for every account. Price the percentage and per-transaction parts against your volume and average ticket, then add monthly, annual and service charges. Compare the yearly total and terms.
Why did my effective rate rise if my markup stayed the same?
The card mix, payment channels, transaction count, refunds or a one-time fee may have changed. Compare matched statement periods and examine each line before attributing the difference to processor markup.
About Payment USA’s Founder
Published by Payment USA, a merchant services provider. Our guides and comparisons reflect that commercial perspective.
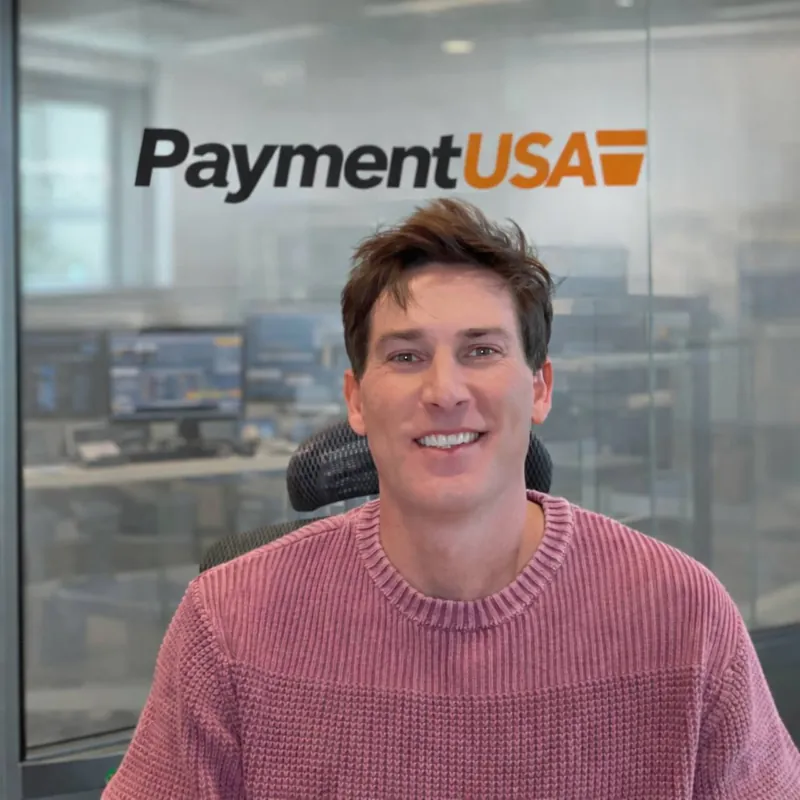
Chase James
CEO, Payment USA
Chase James is the founder and CEO of Payment USA, a merchant services company built on transparency and fair pricing. With over 15 years in the payments industry, Chase has helped thousands of businesses uncover hidden processing fees and switch to honest, interchange-plus pricing.
Contact Chase →